


Non-Conventional Sources of Renewable Energy (FNCRE) in Colombia
Definition
What this term means in the context of investing in Colombia.
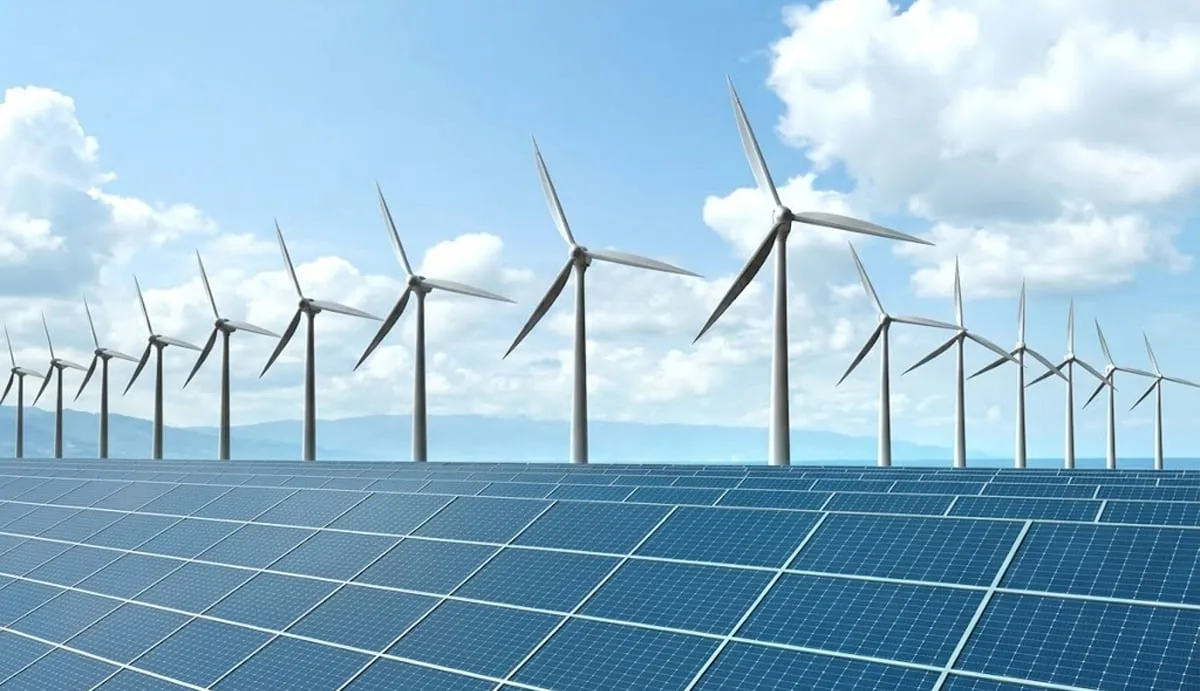
Non-Conventional Sources of Renewable Energy (FNCER) include solar, wind, biomass, and geothermal energy. Their integration into the electricity system was declared a matter of national interest under Law 1715 of 2014.nnFNCER projects are eligible for tax incentives, including income tax deductions, VAT exemptions, customs duty exemptions, and accelerated depreciation.
Learn more: Legal Guide · Government Relations Chapter PDF (opens in a new window)
Sustainability, ESG, and Energy Transition
For now, this is the only term published in this category. More will be added soon.
See the full glossaryAlso in: Strategic Sectors for Investment
Authority, framework and laws
Who regulates this term and which rules govern it.
What regulations govern Non-Conventional Sources of Renewable Energy (FNCER)?
-
2014
Law 1715 of 2014Declares the integration of renewable energy sources to be of national interest and establishes tax incentives.
-
2021
Law 2099 of 2021Energy Transition Law: Expands the regulatory framework for Non-Conventional Energy Sources (FNCE).
-
2023
Law 2294 of 2023Adds white hydrogen to the category of Non-Conventional Sources of Renewable Energy (FNCER).
-
2025
Decree 1033 of 2025Streamlined Environmental License for Solar Projects from 10 to 100 MW (LASolar).
-
2025
Decree 1186 of 2025Streamlined Environmental License for Wind Energy Projects from 10 to 100 MW (LAEólica).
In detail
Types, modalities and key differences for the investor.
Incentives for Non-Conventional Sources of Renewable Energy (FNCER) Projects
The benefits framework established by Law 1715 of 2014, later extended to hydrogen, includes:
| Incentive | What does it consist of? |
|---|---|
| Income Tax | Deduction of 50% of the investment value, for up to 15 years. |
| VAT | Exemption for Equipment and Services |
| Tariffs | Exemption on imported equipment |
| Depreciation | Accelerated depreciation of up to 33.33% per year |
How Is Renewable Energy Sold?
Renewable energy auctions award 15-year, long-term bilateral contracts between generators and electricity retailers. Small-scale self-generators using Non-Conventional Sources of Renewable Energy (FNCER) may receive energy credits for surplus electricity they supply to the grid (CREG Resolution 174 of 2021).
Frequently asked questions
3 answers to the most common questions about this term.
Under Law 1715 of 2014: a deduction of 50% of the investment from income tax for up to 15 years, VAT exemptions for equipment and services, customs duty exemptions on imported equipment, and accelerated depreciation of up to 33.33% per year.
Yes. LASolar (Decree 1033 of 2025) and LAEólica (Decree 1186 of 2025) streamline the environmental licensing process for projects ranging from 10 to 100 MW.
Mechanisms for awarding 15-year, long-term bilateral contracts between electricity generators and retailers, providing revenue stability for renewable energy projects.
This glossary is for informational purposes only and does not constitute legal or tax advice. For investment decisions, consult the regulations in force and a professional advisor.